Kamp 16
Amersfoort
approximately 93.5 m² · Brochure archived 29 July 2026 (the brochure itself is undated)
At asking price
€265,000 excl. buyer's costs
- Total acquisition investment
- €300,746
- Equity required
- €154,996
- Year-one cash-on-cash
- 2.43%
- Annual equity IRR
- 1.26%
Anvest view · 10% target IRR
€181,408 excl. buyer's costs
- Total acquisition investment
- €207,771
- Equity required
- €107,997
- Year-one cash-on-cash
- 7.18%
- Annual equity IRR
- 10.00%
- Levered, per year, including the sale
Gap versus asking price: -€83,592 (-31.54%)
Both columns use the same Anvest base-case assumptions: 10-year hold, 55.00% LTV, 6.75% interest, 7.25% exit yield. The 10% figure is an annual levered equity IRR target, not a year-one cash yield. Editing your scenario below never changes these two columns.
- Total acquisition investment
- The purchase price plus acquisition costs, any allowance for initial works and the financing fee. Later capital expenditure is not included here; it appears in the cash flows of the year it falls.
- Year-one cash-on-cash
- The first year's cash left over after interest and scheduled principal repayments, divided by the equity put in at completion.
Anvest base case · draft, and your scenario
The base case is frozen and does not change when you edit anything. Your scenario is temporary: it is not saved and disappears when you leave the page. Assumed completion: 30 September 2026.
Assumed reletting scenario
A hypothetical assumption. No new lease has been agreed or supplied.
- Current lease runs to
- 31 December 2030
- Modelled vacancy
- 1 January 2031 to 30 September 2031
- New lease
- 1 October 2031 to 30 September 2041
- New annual rent
- €22,446.67
- Refurbishment (one-off)
- €25,000.00
- Letting fee (one-off)
- €0.00
Maximum purchase price at a 10.00% target return
€181,408
Purchase price excluding buyer's costs. Including transfer tax and other acquisition costs the total investment is €207,771, of which €1,497 is a one-off financing fee.
Difference from the asking price: -€83,592
This is the purchase price at which the chosen target return is met exactly. It is not a recommended bid.
Comparison
| Metric | Anvest base case | Your scenario |
|---|---|---|
| Total acquisition investmentPurchase price, transfer tax, other costs and any financing fee | €300,746 | €300,746 |
| Financing feeOne-off, funded at completion | €2,186 | €2,186 |
| Loan | €145,750 | €145,750 |
| Equity required | €154,996 | €154,996 |
| Year-one NOIRent less owner costs, before financing | €16,426.72 | €16,426.72 |
| Year-one net property yieldNOI over the asset acquisition cost, before any financing fee | 5.50% | 5.50% |
| Year-one cash-on-cashCash flow after interest and scheduled principal, over equity | 2.43% | 2.43% |
| Annual equity IRRPer year, including the sale | 1.26% | 1.26% |
| Unlevered IRRExcludes the loan and the financing fee | 3.89% | 3.89% |
| Sale value at exit | €276,194 | €276,194 |
Year-one cash flow build-up
- Rent collected€20,330.64
- Fixed owner costs-€3,294.00
- Variable costs-€609.92
- NOI€16,426.72
- Interest-€9,747.94
- Principal-€2,915.00
- Equity cash flow€3,763.78
Amounts for year one. Negative items are outgoings; the bars show relative size.
Cash flow by year
Scroll sideways to see every column.
| Year | NOI | Interest | Principal | Refurbishment | Letting fee | Operating | Sale | Total | Closing loan |
|---|---|---|---|---|---|---|---|---|---|
| 1 | €16,426.72 | -€9,747.94 | -€2,915.00 | — | — | €3,763.78 | — | €3,763.78 | €142,835 |
| 2 | €16,755.26 | -€9,551.18 | -€2,915.00 | — | — | €4,289.08 | — | €4,289.08 | €139,920 |
| 3 | €17,090.36 | -€9,354.42 | -€2,915.00 | — | — | €4,820.94 | — | €4,820.94 | €137,005 |
| 4 | €17,432.17 | -€9,157.65 | -€2,915.00 | — | — | €5,359.51 | — | €5,359.51 | €134,090 |
| 5 | €1,771.05 | -€8,960.89 | -€2,915.00 | -€25,000.00 | — | -€35,104.84 | — | -€35,104.84 | €131,175 |
| 6 | €18,136.43 | -€8,764.13 | -€2,915.00 | — | — | €6,457.30 | — | €6,457.30 | €128,260 |
| 7 | €18,499.16 | -€8,567.37 | -€2,915.00 | — | — | €7,016.79 | — | €7,016.79 | €125,345 |
| 8 | €18,869.14 | -€8,370.60 | -€2,915.00 | — | — | €7,583.53 | — | €7,583.53 | €122,430 |
| 9 | €19,246.52 | -€8,173.84 | -€2,915.00 | — | — | €8,157.68 | — | €8,157.68 | €119,515 |
| 10 | €19,631.45 | -€7,977.08 | -€2,915.00 | — | — | €8,739.37 | €154,070.34 | €162,809.71 | €116,600 |
Sale proceeds appear only in the final year and are net of selling costs and repayment of the outstanding loan.
Assumptions and method
The model works in monthly cash flows at month end. Rent is indexed on each acquisition anniversary and stops when the lease ends. Reletting is only included when that scenario is switched on; one-off refurbishment and letting fees are excluded from NOI but included in the cash flow. The sale value is the sum of the twelve modelled months of NOI after the sale date, divided by the exit yield, less selling costs and the outstanding loan. Returns (IRR) are annual and use actual dates. A financing fee, where modelled, is part of the equity funded at completion and is not deducted from cash flow again.
- Completion date
- Model assumption: completion assumed on 30 September 2026.
- Hold period
- Model assumption: ten years, so the modelled sale falls inside the assumed replacement lease.
- Annual rent (excl. VAT)
- Source: brochure, annual rent excluding VAT.
- Rent indexation per year
- Model assumption: 2% indexation per lease year.
- Fixed owner costs per year
- Model assumption: €3,294 per year, being the €2,544 owner's-association contribution from the brochure plus a €750 allowance for other owner costs. Continues during vacancy.
- Indexation of fixed owner costs
- Model assumption: fixed owner costs indexed at 2% per year.
- Variable costs (% of collected rent)
- Model assumption: 3% of collected rent for management and letting-related costs.
- Transfer tax
- Model assumption taken from the source model (10.4%); tax treatment still to be tested.
- Other acquisition costs
- Model assumption: €6,000 of other acquisition costs (due diligence, notary, advice).
- Financing fee (% of the loan)
- Model assumption: a one-off arrangement fee of 1.5% of the initial loan. The fee scales with the loan at every purchase price tested.
- Financing (LTV)
- Model assumption: financing at 55% of the purchase price.
- Interest rate
- Model assumption: 6.75% nominal per year, charged monthly on the opening balance. The loan is assumed to run to the modelled sale; refinancing or maturity is not sourced.
- Amortisation per year (% of the original loan)
- Model assumption: straight-line 2% of the original loan per year.
- Exit yield
- Model assumption: exit yield 7.25%.
- Selling costs
- Model assumption: 2% selling costs.
- Target equity return
- Model assumption: target equity return of 10% per year.
- Purchase price
- Source: asking price costs for buyer per the archived brochure.
- Lease end date
- Model assumption: the brochure states only 2030, so 31 December 2030 is assumed within that year. Not a fact.
- Reletting after the lease ends
- Model assumption: nine months of vacancy after the assumed lease end, a new lease from 1 October 2031 at €22,446.67 (the current rent indexed at 2% for five years), a hypothetical ten-year term, and €25,000 of combined works, agency and incentive costs once at the first vacant month. This is not the five-year extension option mentioned in the brochure.
Investment verdict
Opportunity
A compact city-centre shop in a food-service format that suits Kamp, with income already in place.
Pricing driver
Purchase costs, the owner's-association contribution and the 2030 lease event reduce the return at the asking price.
Principal risk
The executed lease, tenant accounts and title extract are missing, and the conflicting cadastral references need resolving.
Sensitivity of the price at a 10% equity target
Every cell is calculated with the same model, changing only the interest rate and the exit yield by half a percentage point either way. All other Anvest assumptions are held fixed. The centre cell matches the Anvest view above.
| Interest \ exit yield | 6.75% | 7.25% | 7.75% |
|---|---|---|---|
| 6.25% | €192,018 | €184,329 | €177,633 |
| 6.75% | €188,975 | €181,408 | €174,818 |
| 7.25% | €186,026 | €178,578 | €172,090 |
Lease and hold timeline
Completion30 September 2026
Assumed date · Assumed completion date.
Current lease ends31 December 2030
Assumed date · Assumed lease end date: the brochure states only the year 2030, so 31 December 2030 is a model assumption.
Modelled vacancy1 January 2031 – 30 September 2031
Assumed date · Hypothetical void period; fixed owner costs and debt service continue.
Assumed new lease starts1 October 2031
Assumed date · Hypothetical 10-year lease, ending 30 September 2041.
Modelled sale30 September 2036
Assumed date · End of the 10-year hold period.
Illustration
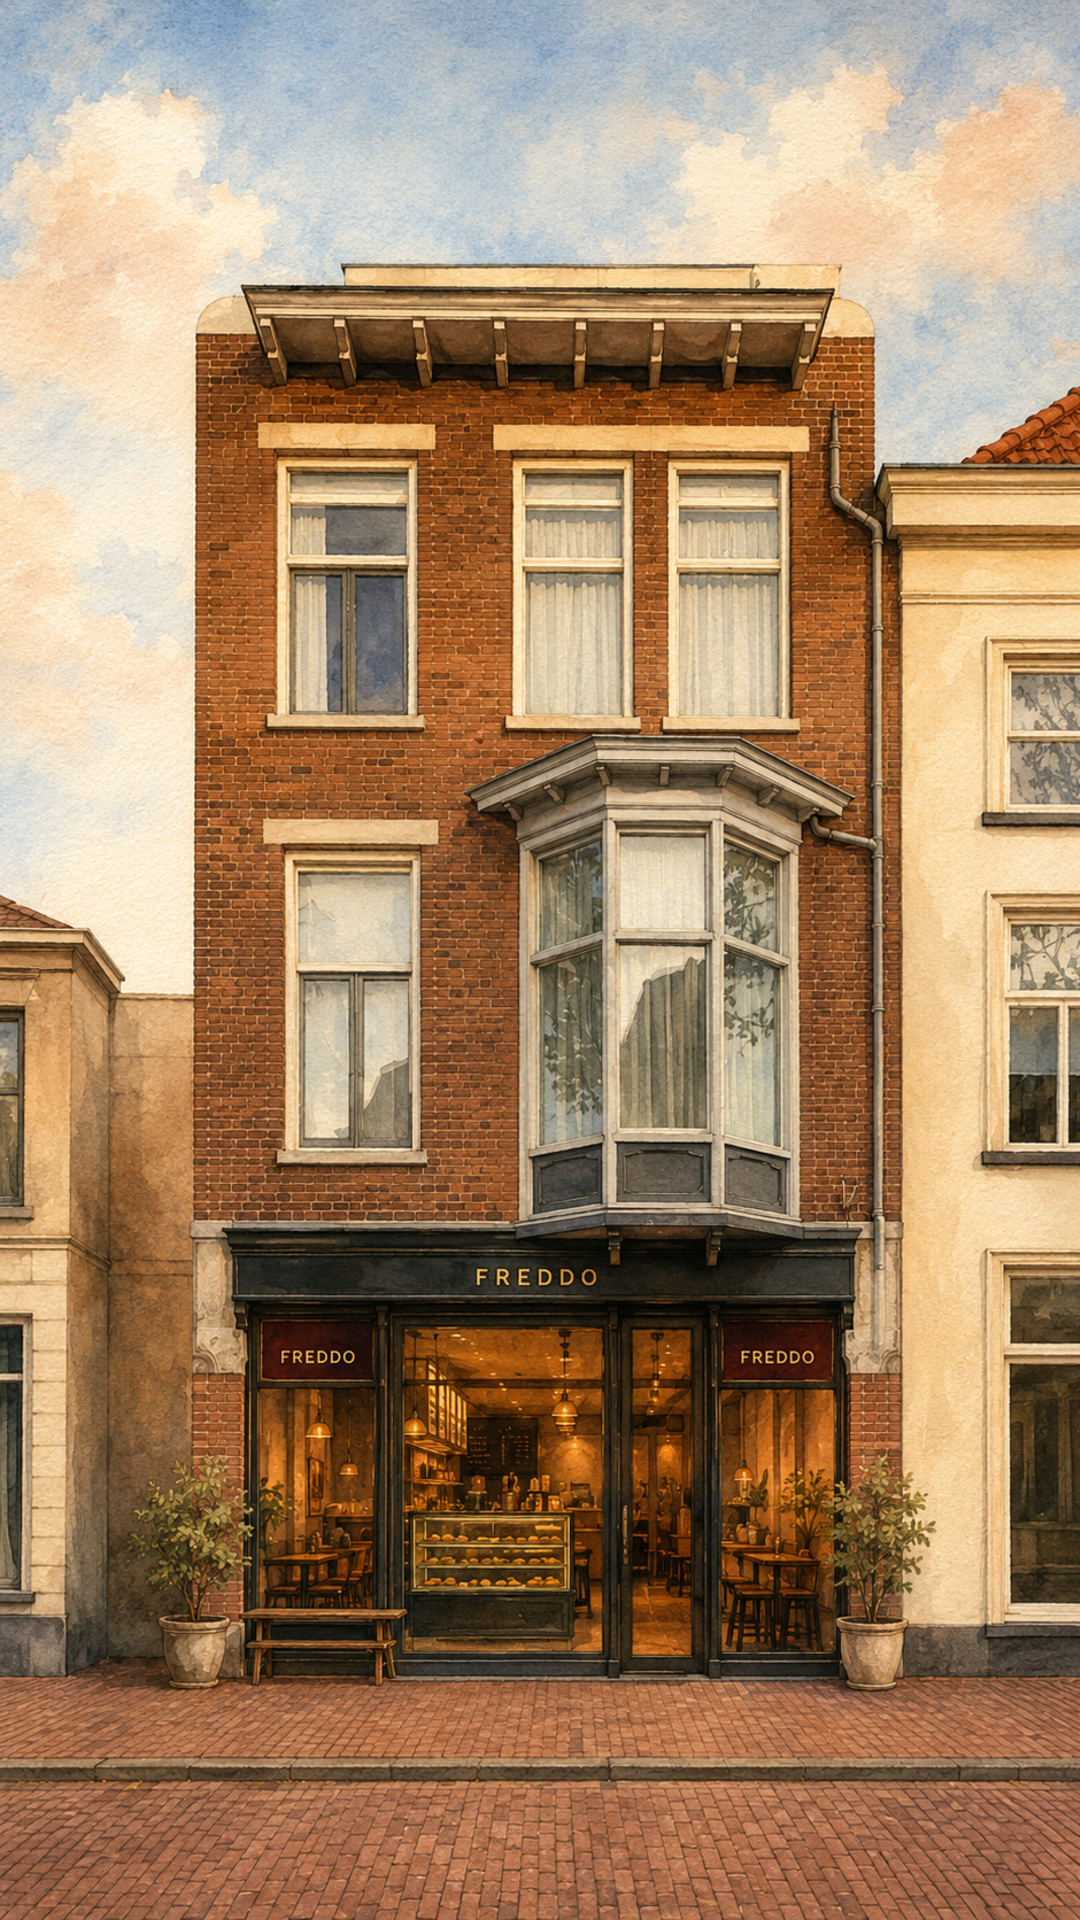
Facts · Brochure archived 29 July 2026 (the brochure itself is undated)
- Asking priceSource
- €265,000 excl. costs
- Asking price, costs for buyer, per the archived brochure. Availability and price have not been re-verified.
- Annual rent (excl. VAT)Source
- €20,331
- Annual rent excluding VAT per the brochure.
- Floor areaSource
- approximately 93.5 m²
- The brochure states approximately 93.5 m². The measurement basis (BVO or VVO) is not stated and is unverified.
- UseSource
- Ground-floor retail unit in café / food-service use
- Per the brochure.
- Lettable unitsSource
- 1
- One lettable retail unit per the brochure.
- Year builtSource
- circa 1800, renovated 2017
- Age and renovation year per the brochure.
- Energy labelSource
- Not provided
- No energy label stated in the brochure.
- Lease endSource
- 2030
- The brochure states the lease runs to 2030, with a possible five-year extension. The exact end date is unknown; the model uses an assumed 31 December 2030 within that year.
- OccupancySource
- The brochure states the unit is let
- No executed lease was supplied. Current availability and price have not been re-verified.
- TenantSource
- Freddo Koffie, Matcha & Sandwich (trading name)
- Trading name per the brochure. The legal tenant entity and covenant are unverified.
Source: Agent's sales brochure, undated, Brochure archived 29 July 2026 (the brochure itself is undated) (agent Comma Vastgoed). Link to the source document. The brochure sits in a restricted Drive folder. The link may ask for access; the folder is not made public and the source file is not published or offered for download here.
Location
Kamp 16, Amersfoort · 3811 AR
Location based on BAG address data.
Source and evidence status
Draft record from an undated brochure archived on 29 July 2026. Not reviewed for publication. No review date recorded.
Sales brochurereceived
Undated; archived 29 July 2026.
Executed leasemissing
Exact lease end date unknown; 31 December 2030 is an assumption.
Tenant covenantunverified
Trading name only; no accounts reviewed.
Title / cadastral referenceconflicting
E 8490 versus E 9236 in the source; requires review.
Owner's associationreceived
€2,544 per year stated in the brochure.
Energy labelmissing
Not provided.
Editorial analysis
Thesis
- Income is in place; the lease evidence determines the bid.
- Kamp is an established city-centre street in Amersfoort, and the food-service format is a plausible long-term use for this size of unit.
- The modelled case runs to a 2030 lease event and an explicit, hypothetical reletting; the return therefore depends on assumptions, not on a contract that has been reviewed.
Potential
- Market rent: how does the contract rent compare with recent food-service lettings on Kamp? Not researched.
- Lease extension: the brochure mentions a possible five-year extension. Whether that option exists, and on which terms, is unverified.
- A lower purchase price feeds straight into the return; the calculator shows how much.
Open questions
- Lease terms and tenant: what does the executed lease say, what is the exact end date, and who is the contractual tenant?
- Owner's association: the brochure states €2,544 per year. What is in the long-term maintenance plan and what reserves exist?
- Title: the source shows conflicting cadastral references (E 8490 and E 9236). Which parcel is being sold?
Scenario outcomes, not a guarantee of value. Source information and assumptions must be reviewed before publication. Status: draft, version 0.1, not reviewed, not published. Source moment 29 July 2026.